MANUFACTURERS RAMP UP PURCHASING IN SEPTEMBER AS GLOBAL DEMAND STRENGTHENS: GEP GLOBAL SUPPLY CHAIN VOLATILITY INDEX
- Global purchasing activity growth climbed close to its 2026 high, pointing to firmer manufacturing output in Q4
- All three major regions register stronger purchasing, with the US, Germany, Taiwan and South Korea seeing accelerated factory buying in particular
- Supply shortages increase for the first time since May as intensified energy crisis hits oil and oil-based products
CLARK, N.J., Oct. 12, 2026 /PRNewswire/ -- GEP Global Supply Chain Volatility Index — a leading indicator tracking demand conditions, shortages, transportation costs, inventories and backlogs, based on a monthly survey of 27,000 businesses — showed global manufacturers ramping up purchases of raw materials and components in September as underlying demand strengthened.
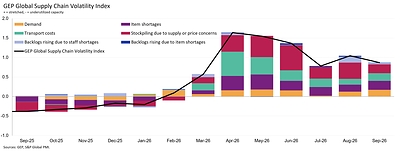
Global input demand growth rose to its strongest since May and was close to its 2026 high, signaling firmer manufacturing activity heading into the fourth quarter. Purchasing strengthened across North America, Asia and Europe, with particularly strong increases in the United States, Germany, Taiwan and South Korea.
At the same time, supply pressures intensified. Shortages increased for the first time since May, while global transportation costs also rose. Shortages of oil and oil-based products were particularly acute, creating renewed cost and availability pressures for manufacturers.
"Manufacturers are buying more because demand is strengthening, but they're doing so at a time when shortages and transportation costs are starting to rise again," said John Piatek, vice president, GEP Consulting. "For companies, that means the priority shifts from simply protecting inventory to securing supply and controlling costs. If demand continues to build through the fourth quarter, businesses that wait will face tighter availability and higher input costs."
Interpreting the data:
Index > 0, supply chain capacity is being stretched. The further above 0, the more stretched supply chains are.
Index < 0, supply chain capacity is being underutilized. The further below 0, the more underutilized supply chains are.
SEPTEMBER 2026 REGIONAL KEY FINDINGS
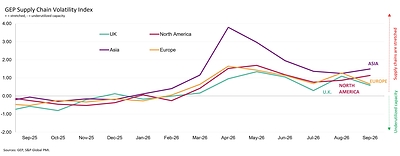
- ASIA: Index rose to 1.49, from 1.24, a three-month high, as stronger demand from Asian factories coincided with tighter supply conditions.
- NORTH AMERICA: Index rose to 1.13, from 0.87, its highest level since June, driven by a resurgence in the U.S. manufacturing economy.
- EUROPE: Index falls sharply to 0.66, from 1.27, indicating lowest level of supply-chain disruption across the continent since March.
- U.K.: Index drops to 0.59, from 1.10, as U.K. manufacturers pare back stockpiling activity, alleviating supply pressure.
SEPTEMBER 2026 KEY FINDINGS
- DEMAND: Global manufacturers purchased more raw materials, commodities and components in September. In fact, the rate of growth rose to a four-month high and was close to its 2026 high, reflected stronger buying activity across many large industrial players such as the US, Germany, South Korea and Taiwan.
- INVENTORIES: Reports of safety buffers being added to inventories fell further during September, marking a sustained reduction since peaking in June. They were still historically high overall, however, signaling that global procurement managers still preferred to hold excesses on hand to mitigate inflation and shortages.
- MATERIAL SHORTAGES: The items in short supply indicator rose for the first time since May in September, indicating a worsening of availability for critical manufacturing inputs. Underlying data revealed a marked rise in shortages for oil and oil-based products.
- LABOR SHORTAGES: Reports of backlogged orders increasing due to staff shortages fell in September, signaling that workforce capacity was less of a constraint on global supply chains.
- TRANSPORTATION: With global oil prices climbing higher throughout September, transportation cost inflation intensified. This marked the first time since April that global logistics prices have increased (on average).
For more information, visit www.gep.com/volatility.
Note: Full historical data dating back to January 2005 is available for subscription. Please contact economics@spglobal.com.
The next release of the GEP Global Supply Chain Volatility Index will be 8 a.m. ET, Nov. 11, 2026.
About the GEP Global Supply Chain Volatility Index
The GEP Global Supply Chain Volatility Index is produced by S&P Global and GEP. It is derived from S&P Global's PMI® surveys, sent to companies in over 40 countries, totaling around 27,000 companies. The headline figure is a weighted sum of six sub-indices derived from PMI data, PMI Comments Trackers and PMI Commodity Price & Supply Indicators compiled by S&P Global.
- A value above 0 indicates that supply chain capacity is being stretched and supply chain volatility is increasing. The further above 0, the greater the extent to which capacity is being stretched.
- A value below 0 indicates that supply chain capacity is being underutilized, reducing supply chain volatility. The further below 0, the greater the extent to which capacity is being underutilized.
A Supply Chain Volatility Index is also published at a regional level for Europe, Asia, North America and the U.K. For more information about the methodology, click here.
Media Contacts
Derek Creevey
Director, Public Relations
GEP
Phone: +1 646-276-4579
Email: derek.creevey@gep.com
Joe Hayes
Senior Principal Economist
S&P Global Market Intelligence
Phone: +44-1344-328-099
Email: joe.hayes@spglobal.com
 View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/manufacturers-ramp-up-purchasing-in-september-as-global-demand-strengthens-gep-global-supply-chain-volatility-index-302905220.html